
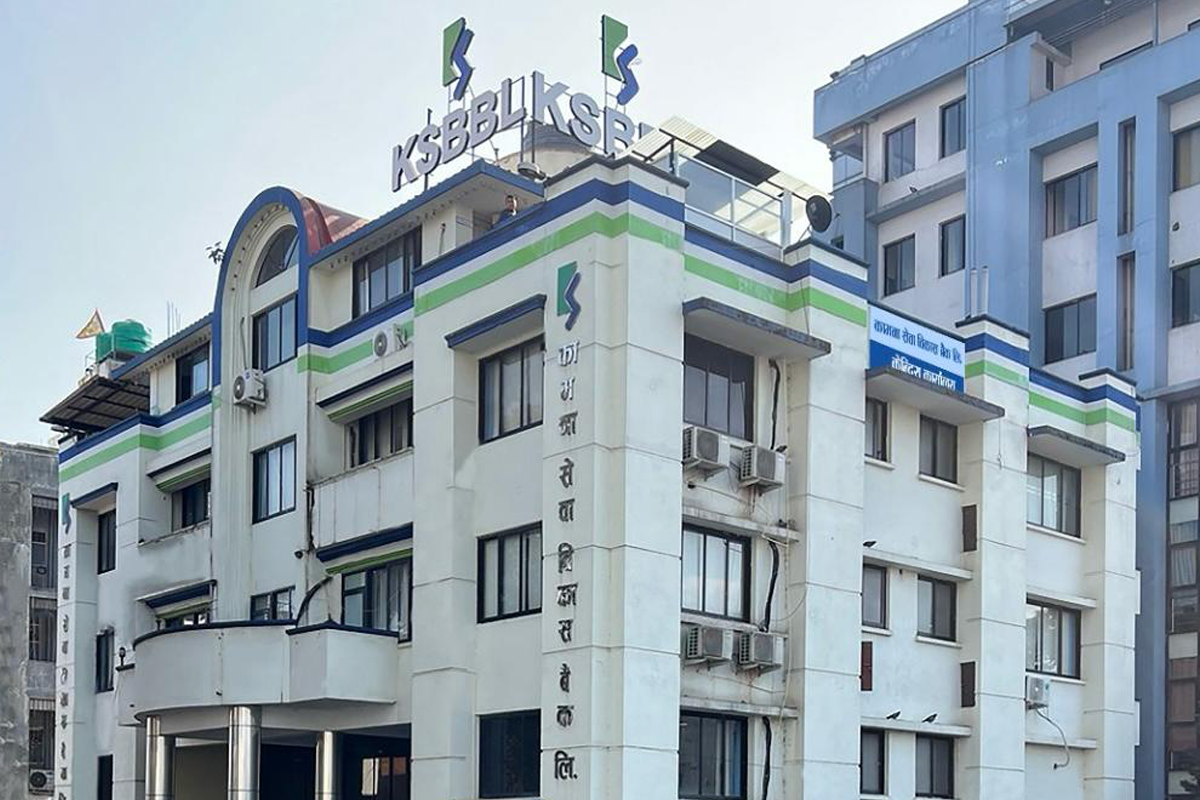
Kathmandu. Kamana Seva Bikas Bank has earned a net profit of Rs. This is 16.99 percent more than the same period of last financial year.
The bank had earned a net profit of Rs. During the review period, the net profit of the bank has increased by 3 crore 35 lakh 71 thousand rupees.
Net interest income of the bank has also increased in the first quarter of the current financial year. The net interest income which was Rs 61 crore 76 lakh 36 thousand in the first quarter of last year has increased to Rs 62 crore 64 lakh 87 thousand in the same period of the current year. This is an increase of 1.43 percent.
By the end of October, the bank has earned 11 crore 2 lakh 36 thousand rupees in net fee and commission income. During this period, the total operating income of the bank is 745 million 840 thousand rupees and the operating profit is 33 million 87 million 70 thousand rupees.
During the review period, the distributable profit of the bank has reached Rs. According to this, the dividend capacity of the bank is 15.76 percent.
The paid-up capital of the bank is 4 billion 21 million 19 million 30 thousand rupees, while 2 billion 22 million 83 million 87 thousand rupees are accumulated in the reserve fund.
The bank has also increased towards deposit collection and loan investment. By the end of last October, the bank has collected deposits of 67 billion 90 million 47 lakh 9 thousand rupees and disbursed loans of 56 billion 34 million 53 lakh 33 thousand rupees.
During the same period of the last financial year, bank deposits were 66 billion 17 billion 75 lakh 24 thousand rupees and loan investment was 54 billion 20 million 38 lakh 71 thousand rupees. Accordingly, bank deposits increased by 2.60 percent and loan investment by 3.95 percent.
The bank’s earnings per share have also increased. Earnings per share increased from Rs 20 46 paisa in the first quarter of last year to Rs 23 13 paisa during the review period of the current year. The net worth per share of the bank is Rs 161 84 paise and the price earnings ratio is 20.58 times. Thus, the bank has succeeded in reducing the bad loan ratio. At the end of October of last financial year, the bad loans decreased to 3.93 percent in the same period of the current year which was 4.41 percent.
Along with the decrease in bad loans, the bank’s impairment charges related to loan loss provisions have also decreased. In the first quarter of last year, this charge, which was Rs. 116 million, has been reduced to Rs. 494 million in the review period of the current year.